Vietnam's minimart market is expanding rapidly, with experts forecasting about 30,000 minimarts by 2030, up from about 10,000 today. At a forum on retail channel volatility and e-commerce organized by the High-Quality Vietnamese Enterprise Association (HVNCLC), market researchers from the Business Research and Support Center (BSA) said that the traditional retail channel will gradually lose market share but remain resilient, while minimart numbers are set to rise sharply, shifting the battleground toward suburban areas. By 2030 the minimart count could triple, reaching more than 30,000 stores with growth rates staying above 20% per year.
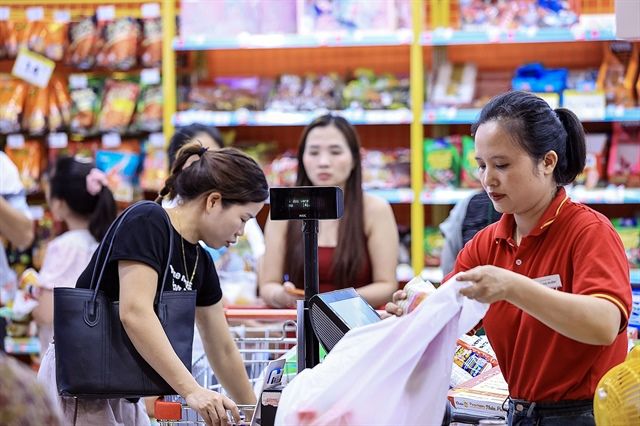
The expansion is driven by changes in consumer shopping behavior and the push to meet convenient shopping needs. Retail systems and e-commerce platforms are shifting strategy toward suburban and rural areas to unlock future growth, leveraging lower lease costs there. The market is also seeing increased activity from foreign chains entering Vietnam, while domestic minimart chains continue to hold the upper hand. The success of the minimart model is tied to meeting urban residents’ after-work shopping needs, with the period from 17:00 to 21:00 identified as the “golden hours” for these outlets. The race for market share also creates opportunities for rural consumers to access modern retail, including ultra-fast delivery under 2 hours.
Minimart growth has accelerated in recent years. The average pace of new openings has been 5 minimarts per day, about 1,500-2,000 per year. But the pace has now reached 10 minimarts per day. Major domestic players—WinMart/WinMart+ (Masan Group), Co.opmart/Co.op Food (Saigon Co.op), Bach Hoa Xanh, and Satramart/Satrafoods (Satra)—continue to dominate the market. The business model’s momentum is supported by consumer behavior shifts and the ongoing modernization of traditional channels as new distribution models emerge and competition intensifies.
Traditional grocers and supermarkets are modernizing in response to the minimart expansion. As new distribution models emerge and competition increases, traditional stores are adjusting their business models, reorganizing operations, and improving services to stay competitive. The expansion also enhances access to modern retail for rural consumers, particularly through improved delivery options that support shorter delivery times.
Mr. Đinh Công Trí, Senior Strategic Business Director of TT Group, said that GT can adapt very flexibly. “The two forms of grocery stores—traditional and upgraded—will be the groups with notable conversion speed in the near future.” He noted that Vietnam currently has about 550,000-600,000 traditional retail outlets, with small grocery stores accounting for about 70-75% of the total and the remainder mainly department stores and other specialized formats. From 2026-2030, GT will continue transforming along four main directions: modernization, differentiation, digitization, and specialization. Modernization in GT will be most evident in the grocery sector, including traditional groceries and large-scale grocery hypermarkets, with shelf layouts similar to modern retail stores. He cited examples of traditional grocery stores that have proactively improved displays and product arrangements to create a more professional shopping environment.
Mr. Trí emphasized that traditional stores are differentiating by value: a segment of high-income consumers increasingly cares about experience, quality, and premium product lines at traditional stores, while price-sensitive customers prioritize family budgets and product prices. This requires stores to adjust product assortments to reflect local customer characteristics rather than focusing only on everyday items as before.