Valuing F88: Decoding the Retail Formula in a Consumer
Finance Company
The public offering of F88 (UPCoM: F88) presents an intriguing valuation puzzle for the equity
market. While many investors still weigh this company against traditional banks, analysts offer a different perspective: the core operating model of F88 resembles a high-growth retail chain with strong operating leverage, not merely a lending institution.
Retail financial services: A benchmark for value
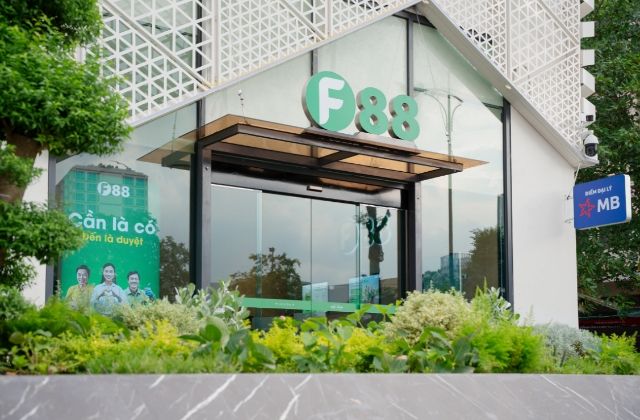
To understand why financial institutions are willing to pay a premium for F88, one must unpack the fundamental difference between a retail-finance model and traditional intermediation. Unlike traditional banks, where lending is heavily influenced by corporate clients and constrained by credit room and strict capital adequacy and branch-expansion rules, F88 focuses on serving customers who lack full access to banking services, operating as a mass retail network with virtually unlimited physical outlets.
Not bound by credit room, F88 has a strong incentive to push forward by saturating physical locations; its store density is even higher than many banks, making it an effective extension to reach rural, lower-income customers. F88 can also design secured-loan packages with small collateral based on vehicle registrations, with flexible tenors.
In the latest analyst reports, both Maybank Securities (MSVN) and Vietcap do not start their discussion by comparing F88 with listed banks. Instead, they view F88 through the lens of a retail-finance model where value is determined by the ability to scale the network, grow the number of customers, and increase the value captured at each touchpoint.
One of the main value drivers for F88 as a growth company is the size of the market opportunity, which remains large. According to FiinGroup's industry report, the Vietnamese pawn-loan market is estimated at about
USD 10.3 billion with expected CAGR of 17-20% over the next five years. Notably, modern pawn chains currently account for only about 3% of the national market.
With a position as the leading player holding roughly 85% of the market share in the new-generation pawn industry, F88 has ample long-term room to expand loan volumes and scale further. The company is targeting to raise the number of customers served from 1.6 million to 5 million by 2030, while maintaining average annual revenue and net profit growth of around 30% over 2026-2030.
Scale effects of the store network and growth leverage from existing stores
According to Vietcap's analysis, F88 shares strong similarities with the classic investment story of mobile phone/electronics retail in the previous decade. Both succeed by standardizing a fragmented market with a uniform, modern store network.
As store scale matures, fixed costs (such as technology and infrastructure) are spread across each branch, helping margins expand.
The strength of this retail formula is evidenced by F88's own data: by June 2026, the company had the largest nationwide network with 976 service rooms across 34 provinces. Notably, 99% of the system's rooms that are more than a year old have already been profitable, with pretax profit per room averaging VND 976 million in 2025.
According to PSI's update, improved operating efficiency helped F88 report explosive first-quarter 2026 results, with pretax profit of VND 303 billion, up 129.4% year over year.
The Phygital multi-channel model and revenue rotation beyond lending interest
F88's value is not limited to traditional pawn-lending. The value of the business also lies in its ability to scale the Phygital model—seamlessly integrating physical touchpoints with digital capabilities.
F88 says its MyF88 super app for the mass segment surpassed 900,000 users as of June 2026, helping to lift the customer revisit rate to an impressive 54.7%, thereby optimizing the customer lifetime value and reducing operating costs.
At the same time, F88 is diversifying non-credit revenue. In Q1 2026, insurance distribution via its subsidiary Ngôi Nhà Xanh grew 93%, reaching VND 169 billion and accounting for 16% of total system revenue.
Both Vietcap and MSVN agree that this micro-insurance line is transforming into a real growth engine rather than a mere add-on to lending. MSVN notes that income from insurance fees and other non-interest services will be the core driver of F88's profitability going forward, reducing dependence on balance-sheet expansion.
F88 targets by 2030 to raise the share of non-credit revenue to about 20% of total revenue. The combination of an 'agency banking' model with large banks allows F88 to tap a rich customer base without bearing heavy capital constraints, freeing balance-sheet capacity and enhancing ROE efficiency.
Industry dynamics: The 2025 decree recognizing title lending
FiinGroup notes that the implementation of Decree 282/2025/NĐ-CP is a major breakthrough, officially recognizing the legality of asset-free vehicle-title lending—one of F88's core products. This strengthens F88's position as a regulated pawn chain, distinct from illegal lending.
Valuation: Investment opportunities at discounted prices
Thanks to macro-supportive factors and efficient operations, brokerages forecast a very positive financial outlook for F88, creating compelling valuation perspectives.
MSVN's forecast projects net profit growth of 35% in 2026 and a 28% average growth in 2027-2028, with ROE of 26-31%. Using a relative valuation approach based on historical M&A deals in the Southeast Asian pawn-lending sector (trading at median P/E 23x and P/B 4x), MSVN sets a target price for F88 of up to VND 200,000 per share (post-split equivalent to VND 100,000).
Vietcap's view supports the same narrative: the strong earnings performance confirms that network scale is translating into real profits. The projected 2026 net profit for the parent company is VND 1,168 billion, rising to VND 1,677 billion in 2027. F88's profitability is among the market's best, with ROE projected to peak at 39.1% in 2026 and to average around 33% over 2026-2030, outpacing the 2025 industry average of 10.7% (FiinGroup).
With these bright financial prospects and dominant position, Vietcap recommends buying F88 at a target price of VND 98,000 per share, about 38% above the issue price of VND 71,000.
JSI's recommendation: Buy F88 with a target of VND 114,000 per share (implying roughly 45.6% potential return from the market price of about VND 79,000 at the report date 03/07/2026).
F88 is currently trading at forward P/E for 2027 of 11.07x, which suggests the market is underpricing the company’s growth potential. The ROE premium rationale includes a projected 2027 EPS of VND 7,073, supporting a target price of VND 114,000.
If you want to read more, Fili and other brokerages provide additional insights.